Bakersfield, CA | Accident Settlements
Understanding What Shapes an Accident Settlement in Bakersfield
Medical care, bills, lost income, insurance coverage, and the facts of your case all play a role in settlement discussions. Your first consultation with Colvin Accident Lawyers is free, confidential, and carries no obligation to continue.
By Donald Norman Colvin · Published November 1, 2026
Hypothetical Example: How a $100k Settlement Could Be Divided
Hypothetical example only, not a prediction of any case’s value. Amounts after fees and costs are usually less than the headline number. A $100,000 settlement is a gross figure, the total agreed before anything is taken out. Fees, case costs, medical liens, and any fault reduction can come out before money reaches the injured person.
If you’re reading this, you may have an offer letter in hand. Or you may be helping a family member whose claim is still open. Either way, the headline number is only the starting point. This guide explains what usually comes out and why. It uses a clearly labeled hypothetical, not a prediction about any real case.
If an insurer's offer is sitting unanswered while you or a loved one recovers, we're glad to help you read it with the net amount in mind. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Why a $100,000 settlement is usually a gross number
A settlement figure is the total amount the at-fault party or its insurer agrees to pay. It comes before any deductions. Think of it like gross pay on a paycheck. The number at the top is not the money that lands in your account.
Net is what remains after costs, fees, liens, and other required payments come out. Gross is the headline. Net is what you actually keep. Most people feel the gap when the bills arrive.
Your own bills are often the largest items. Medical charges, health plan payments, and provider balances must be identified and settled. Lost wages and out-of-pocket costs also belong in the math.
When you read an offer letter, start with three questions. Is the amount one lump sum? Does it cover property damage or only injuries? Does it say anything about liens or who will be paid from it? The answers shape the net amount more than the headline does.
How settlement payments are calculated
A settlement reflects the damages a claim can support. Under Cal. Civ. Code § 1431.2, in any action for personal injury, property damage, or wrongful death based on principles of comparative fault, a defendant’s liability for non-economic damages is several only and not joint, so each defendant is liable only for the amount of non-economic damages allocated to it in direct proportion to its percentage of fault. Economic damages are objectively verifiable monetary losses, such as medical expenses, loss of earnings, and costs of repair or replacement. Civil Code § 1431.2 defines these terms.
Non-economic damages are subjective, non-monetary losses. They include pain, suffering, inconvenience, emotional distress, and loss of companionship. These losses come with no price tag printed on a bill. Adjusters and attorneys look at the injury, the medical records, and how it changes daily life.
Economic losses rely on paper. Bills, pay stubs, and repair estimates prove them. Non-economic losses rely on a clear record of how the injury affects your life. Both need solid support to carry weight in a claim.
Property damage is usually handled as a separate claim from bodily injury. A vehicle repair may follow its own track. Check whether a stated settlement figure includes it, because offer letters don’t always say.
Deductions: attorney fees and case costs
That agreement is where the calculation is set out. Business and Professions Code § 6147 requires a contingency fee contract, other than one for recovering workers’ compensation benefits, to be in writing and signed by both the attorney and the client, and requires the attorney to provide a duplicate copy of the signed contract to the client at the time the contract is entered into. The contract must state the fee rate. It must also explain how disbursements and costs affect the fee and the client’s recovery.
The statute also says a contract that fails these requirements is voidable at the client’s option, and the attorney is then entitled to collect a reasonable fee. Read the agreement closely before you sign anything. Ask where the fee and costs are calculated.
Case costs are the out-of-pocket expenses needed to prove the claim. They can include medical records fees, costs for reviewing records, and filing costs. These costs come out of the recovery, so they lower the net amount. Ask for a written list of costs as the case moves forward.
The agreement sets the order of the subtractions. Read it to see whether the fee comes off before costs or after. The order changes the math, so don’t guess.
Medical bills, liens, and reimbursement claims
Some medical providers hold liens against a settlement. Health plans, and in some cases public programs, may also ask to be repaid for care they covered. These reimbursement claims can cut the net amount.
Unpaid balances from the accident must be identified and resolved before money is paid out. That is why the net figure can be lower than the gross, sometimes by a lot. For example, $20,000 in liens and reimbursement claims comes straight off the top after fees and costs.
Ask for an itemized list of every lien and reimbursement claim tied to the case. Put that request to the claim handler in writing. A clear list makes the net figure easier to check, and it shows what still needs to be resolved.
Don’t assume a bill is paid or closed. Confirm each balance before you count the money as yours.
Comparative fault can reduce the total
Your own share of fault reduces your recovery.
Here is a hypothetical. Suppose total damages are $100,000, and a finding puts 20% of the fault on the injured person. The recoverable amount becomes $80,000 before fees, costs, and liens come out.
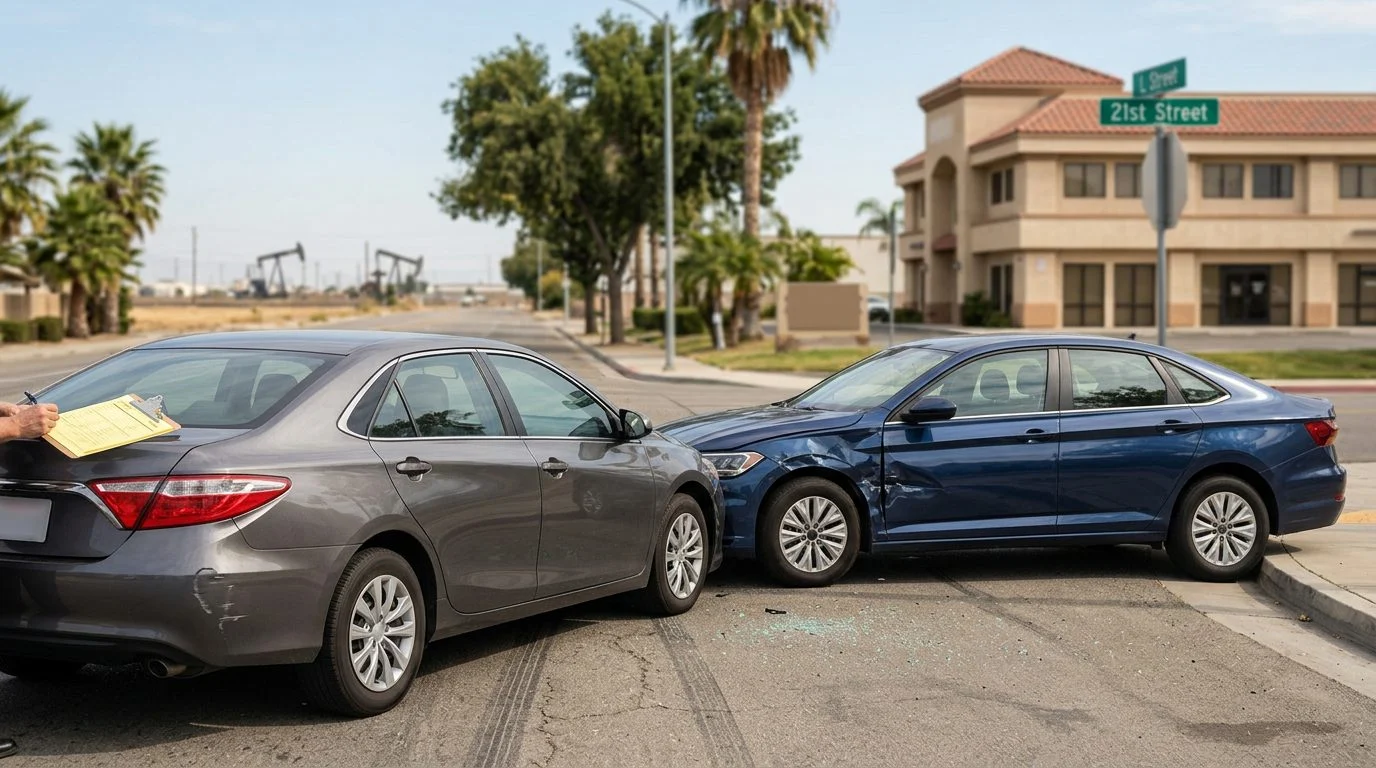
Fault disputes are common in intersection, lane-change, and pedestrian crashes. In a marked crosswalk, a driver must yield to a pedestrian.
Seat belts can come up too. A defendant may argue that not wearing an available seat belt made injuries worse. It is not an automatic bar.
Motor vehicle claims have another limit. Civil Code § 3333.4 bars recovery of non-economic losses in some cases, such as when the injured driver was convicted of drunk driving or did not carry required insurance. The statute has exceptions, so the facts matter.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Are settlement payments taxable?
Tax questions can come up with a settlement, and the answer depends on how the money is structured and what it pays for. Some parts of a payment may be handled differently from others. The breakdown in the settlement paperwork matters.
Read any release before you sign it. A release is the document that ends the claim. Check what it says about the amount, the liens, and who gets paid. Keep copies of every document in one place.
A worked example with a hypothetical $100,000 settlement
This example is hypothetical. It is not a prediction of any real case’s value. The dollar amounts are placeholders used only to show the arithmetic.
- Step 1, gross settlement: $100,000.
- Step 4, medical liens and reimbursement claims: any amount owed to a lienholder or reimbursement claimant is subtracted at this step.
- Step 5, other lawful payments: none in this example.
- Net amount: the amount left after the gross recovery is reduced by attorney’s fees, case costs, and any liens.
The fee and the liens move this result the most, because they are the largest items. Small changes in costs matter less, but they still add up.
The same $100,000 gross can produce very different net amounts. The facts of the case, the liens involved, and the terms of the fee agreement all change the result. Compare the net figure, not the headline, when you review any offer.
Does more medical treatment, such as injections, raise the number?
Treatment alone does not raise a settlement. Care matters because it creates records of the injury, the care it needed, and the costs. When a doctor prescribes injections, they become part of that medical record like any other treatment.
What makes a difference is whether the records tie the injury to the accident. They should also show how the injury affects daily life, work, and family. A record that connects these dots tells a clearer story.
Gaps in treatment can be raised by the other side. Keep appointments, follow the care plan, and keep copies of records. Consistent care helps the claim show a clear and continuous picture of the injury.
Frequently asked questions
How much of a $25,000 settlement will I get?
The same deductions apply at a smaller total, including fees, costs, liens, and any fault share. The net amount depends on the facts of the case.
How long does it take for a settlement to be paid out?
Payment follows the signed release, the resolution of liens, and the fee agreement. Timing varies by case.
Do I have to accept the first offer?
No, you decide whether to accept any offer. In a lawsuit, a formal offer under Code of Civil Procedure § 998 is deemed withdrawn if it is not accepted before trial or arbitration or within 30 days, whichever comes first. If you turn down a defendant’s offer and do not get a more favorable result, you cannot recover your costs after the offer and must pay the defendant’s costs from the time of the offer.
What if I’m not sure whether a bill or lien should be paid from the settlement?
Identify and document every bill and lien before you treat the net figure as final. Ask the claim handler for a written list of every lien and reimbursement claim.
Key takeaways and your next step
So, how much of a $100k settlement will I get? Usually less than the headline. Here is what to remember:
- Gross is the headline. Net is the amount that matters.
- Deductions can include fees, case costs, liens, reimbursement claims, and any fault reduction.
- The written fee agreement sets how the fee and costs are calculated.
- Ask for an itemized list of every lien before you count the money.
If you’re reviewing an insurer’s offer while someone you care about is still recovering, you don’t have to work through the numbers alone. Our first consultation is free, confidential, and comes with no obligation to continue. You can reach out through our contact page.
Donald Norman Colvin, Colvin Accident Lawyers, Bakersfield, California — responsible for this site.
Key Factors in a Settlement Discussion
Medical treatment and bills
Records of your care, the charges billed, and any treatment still ahead all form the documentation a settlement discussion relies on.
Insurance coverage
The policy limits available from the at-fault party's insurer can shape what a settlement discussion looks like.
Lost income
Missed wages and reduced ability to work are documented and discussed as part of the full picture of a claim.
Effects on daily life
Pain, physical limits, and changes to work, family, and daily routines are part of how an injury's impact is described.
Before You Sign Anything
Insurers often make early offers, sometimes before the full extent of an injury is known. Speak with a lawyer before you accept an offer or sign a release.
Questions to Ask Before You Settle
Is my medical picture complete?
Settling before your treatment and prognosis are clear can leave future care costs unaddressed.
Who else may have a claim?
Liens and reimbursement claims can affect what remains after a settlement, so they should be identified early.
Does the offer cover my documented losses?
Compare any offer against your medical records, lost income, and daily impact, not just the bills you have received so far.
How are fees and costs handled?
Ask for the fee agreement in writing, including how case costs are handled, before you agree to representation.