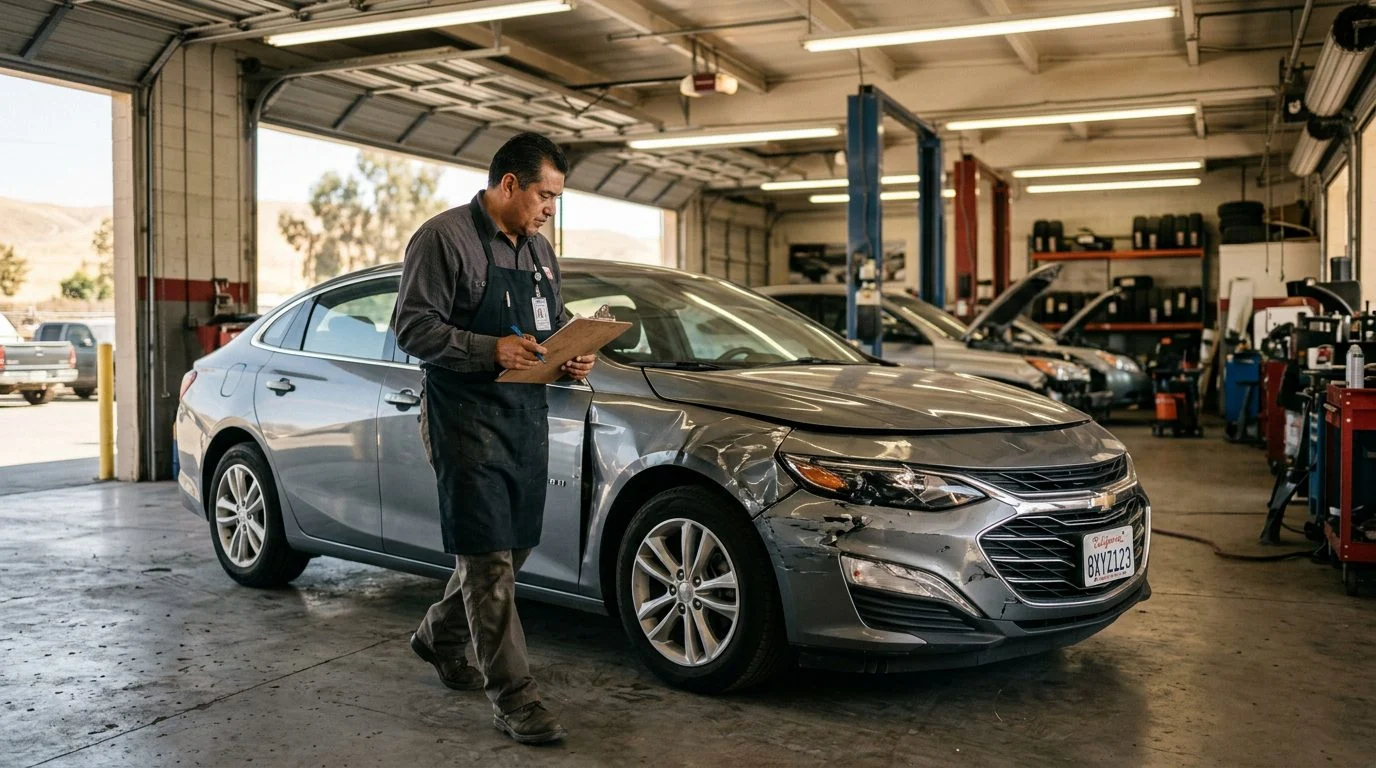
Car Accident Claims in Bakersfield and Kern County
What Shapes a Car Accident Settlement in California
Every claim is built on its own records, medical care, and losses. Here is how the pieces fit together.
By Donald Norman Colvin · Published November 14, 2026
You were hurt in a car crash, or you’re trying to help someone who was. You want to know what a car accident settlement in California could look like, and you want a straight answer.
The short answer is that no single typical amount fits every case. A settlement is built from the losses one injured person can document, the injuries involved, how fault is divided, and the insurance that applies.
Why a Typical Car Accident Settlement Figure Is Hard to Pin Down
A typical car accident settlement figure is hard to pin down because each claim is valued on its own facts. Two crashes that look alike can produce very different claims once the losses are counted.
You may see averages in online articles. An average blends many different cases together, so it rarely matches one person’s medical bills, time off work, or injuries. Insurers and evaluators look at the specific losses in front of them.
The outcome depends on the facts of each case, and results will differ when the facts are different. Use that as your starting point, not any single number.
Think of a settlement as a total built from parts. Each part needs proof. A missing record can leave a real loss out of the picture, which is why documentation comes up again and again in this guide. The sections below cover the law of fault, economic and non-economic losses, injury severity, insurance limits, and timing.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
How California Law Shapes a Car Accident Claim
Negligence is the starting point. Under Civil Code § 1714, everyone is responsible for an injury caused by a want of ordinary care. Cal. Civ. Code § 1714 reads: “(a) Everyone is responsible, not only for the result of his or her willful acts, but also for an injury occasioned to another by his or her want of ordinary care or skill in the management of his or her property or person, except so far as the latter has, willfully or by want of ordinary care, brought the injury upon himself or herself.” In a crash case, that usually means showing the other driver failed to use ordinary care, that this caused the harm, and that the harm has a monetary value.
A claim is usually made against the at-fault driver. That driver’s insurer then evaluates the claim against the coverage in place. Coverage is covered in a later section.
Economic Damages: Medical Expenses and Lost Wages
Economic damages are the objectively verifiable money losses from a crash. Civil Code § 1431.2 lists medical expenses, loss of earnings, loss of use of property, and repair or replacement costs among them.
Medical expenses cover emergency care, hospital stays, imaging, surgery, prescriptions, and future treatment. Bills alone are not enough. The medical records explain why each treatment was needed.
Lost wages cover pay you lost while you could not work. Lost earning capacity covers future income affected by a lasting injury. Pay stubs, an employer letter, and time-off records are the usual proof.
Property damage is a separate category. It covers vehicle repair or a total loss, plus related costs like a rental car.
Civil Code § 3333 measures damages, for the breach of an obligation not arising from contract, as the amount that compensates for all the detriment proximately caused, except where the Code otherwise expressly provides. The California Department of Insurance’s guide on what to do after an accident explains how to report an injury accident and track injuries and related expenses for a claim. Organized records matter because evaluators measure economic losses against documents.
Non-Economic Damages: Pain and Suffering
Non-economic damages are the subjective losses from a crash, such as pain, suffering, emotional distress, and loss of enjoyment of life. The same statute calls these losses subjective and non-monetary, so they are harder to put a value on than medical bills.
Evaluators look at the nature of the injury, how long it lasts, and how it changes daily life. A person who can no longer coach a child’s game or sleep through the night can describe that change in concrete terms.
Consistent treatment helps show these effects. Follow the care plan your doctor gives you, keep your appointments, and write down how pain limits work, chores, and family life.
Fault also shapes the non-economic side. Under Civil Code § 1431.2(a), each defendant pays non-economic damages only in direct proportion to its own percentage of fault.
Motor vehicle claims also face a specific limit. Civil Code § 3333.4(a)(1) bars recovery of non-economic losses for an injured person who was driving under the influence at the time of the crash and was convicted of that offense. Under Civil Code section 3333.4(c), the exception applies only to the uninsured-owner bar in paragraph (2), and only when the injury was caused by a driver convicted of DUI. It does not change the DUI bar in paragraph (1) or the operator bar in paragraph (3), so the facts of the crash, the vehicle’s insurance status, and the conviction all matter.
How Injury Severity Affects the Value of a Claim
Injury severity matters because more serious injuries usually bring more care, more time away from work, and sometimes lasting limits.
Claims often involve soft tissue injuries such as sprains and strains, back and neck injuries, herniated discs, and joint injuries. Fractures and catastrophic injuries, such as spinal cord or brain injuries, usually involve longer treatment and larger future losses.
A diagnosis alone does not decide value. Evaluators look at the diagnosis together with the treatment it required, how long that treatment lasted, and whether a lasting impairment remains.
Gaps in care draw questions. If treatment stops for weeks without a clear medical reason, an adjuster may ask whether the injury had healed. Follow medical advice and keep records of every visit.
More severe or permanent injuries generally bring larger future medical costs and lost earning capacity. Those losses take more work to estimate, which is why they need more detailed records.
Insurance Limits and Fault: What They Mean for a Settlement
A policy’s limits can cap what the at-fault driver’s insurer pays. Coverage is one of the first facts to check.
California sets minimum liability limits. Under Vehicle Code § 16056, for a policy issued or renewed on or after January 1, 2025, the minimum bodily injury liability limit is $30,000 for one person and $60,000 for two or more persons in one accident, and the minimum property damage limit is $15,000. Legal minimum insurance amounts are not a measure of what any claim is worth.
If the at-fault driver has no insurance, your own uninsured motorist coverage may come into play. Insurance Code § 11580.2 defines an uninsured motor vehicle.
Fault is shown through the police report, photographs, witness statements, vehicle damage, and, where available, traffic camera or phone data. In a rear-end collision or a multi-vehicle crash, the key question is usually what the evidence shows about how the impact happened, not the crash type alone.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
How Settlements Are Reached and Why Timing Matters
Most settlements follow a sequence. A claim is submitted, the insurer investigates, the injured person sends a demand, both sides negotiate, and a lawsuit may follow if a fair resolution is not reached.
Timing matters. Code of Civil Procedure § 335.1 sets a two-year limit for an action for injury to a person or for the death of a person caused by another’s wrongful act or neglect. Other deadlines can apply to some claims.
Medical bills may be paid through health insurance or government programs during a claim.
Wrongful death claims follow different rules about who may bring the claim. Code of Civil Procedure § 377.60 names the decedent’s surviving spouse, domestic partner, children, and issue of deceased children, or, if there is no surviving issue, the persons entitled to the decedent’s property by intestate succession. It also allows dependent putative spouses, stepchildren, and parents (or guardians if the parents are deceased), and minors who lived in the decedent’s household for the previous 180 days and depended on the decedent for one-half or more of their support. Death claims fall under the same two-year rule in § 335.1.
Talking With Colvin Accident Lawyers About Your Crash
You may be reading this after a crash you did not choose. The injured person might be a parent, a spouse, a child, or someone who died.
You’re weighing real decisions. You may be deciding whether to pursue a claim, which records to gather now, and how to understand the losses involved. Those choices are easier with someone who can review the details of your crash.
Is there one typical car accident settlement amount in California?
No. Each settlement depends on the documented losses, injuries, fault, and insurance involved.
How long do I have to file a car accident claim in California?
Generally two years, under Code of Civil Procedure § 335.1. Other deadlines can apply.
To learn more about the firm’s wrongful death work, see our wrongful death lawyer page.
If you’re weighing a decision for someone you care about, talk with Colvin Accident Lawyers. “La consulta inicial es gratuita, confidencial y sin compromiso de continuar.” (The initial consultation is free, confidential, and carries no obligation to continue.) Contact Colvin Accident Lawyers to start the conversation.
Colvin Accident Lawyers, Bakersfield, California — responsible for this site. Responsible lawyer: Donald Norman Colvin.
Before You Give a Recorded Statement
An insurance adjuster may ask you for a recorded statement soon after a crash. Speak with a lawyer before you give one, so your words are not used against your claim.
Common Elements in a Car Accident Claim
Medical Care and Records
Emergency treatment, follow-up visits, therapy, and the records that document your injuries.
Lost Income
Wages missed while you recover and any reduced ability to work in the future.
Vehicle and Property Damage
Repair or replacement costs for your vehicle and other property damaged in the collision.
Insurance Coverage
The policies that may apply to the crash, including limits that can affect what is available.
How Colvin Accident Lawyers Can Help
Free First Consultation
The initial consultation is free, confidential, and carries no obligation to continue.
Careful Review of Your Records
We look at medical bills, repair estimates, wage information, and the police report together.
Support for Families and Injured Drivers
Our team works with car accident victims and their loved ones across Kern County and nearby communities.
Serving Bakersfield and Surrounding Areas
We represent clients in Bakersfield, Fresno, Visalia, Lancaster, Palmdale, Delano, and Tehachapi.
Talk With Colvin Accident Lawyers About Your Car Accident Claim
Related practice areas
- Fatal Drunk Driver Crash Wrongful Death Lawyer in Kern County
- Does a Wrongful Death Settlement Need Court Approval in California?
- California Wrongful Death Statute of Limitations: Two Years