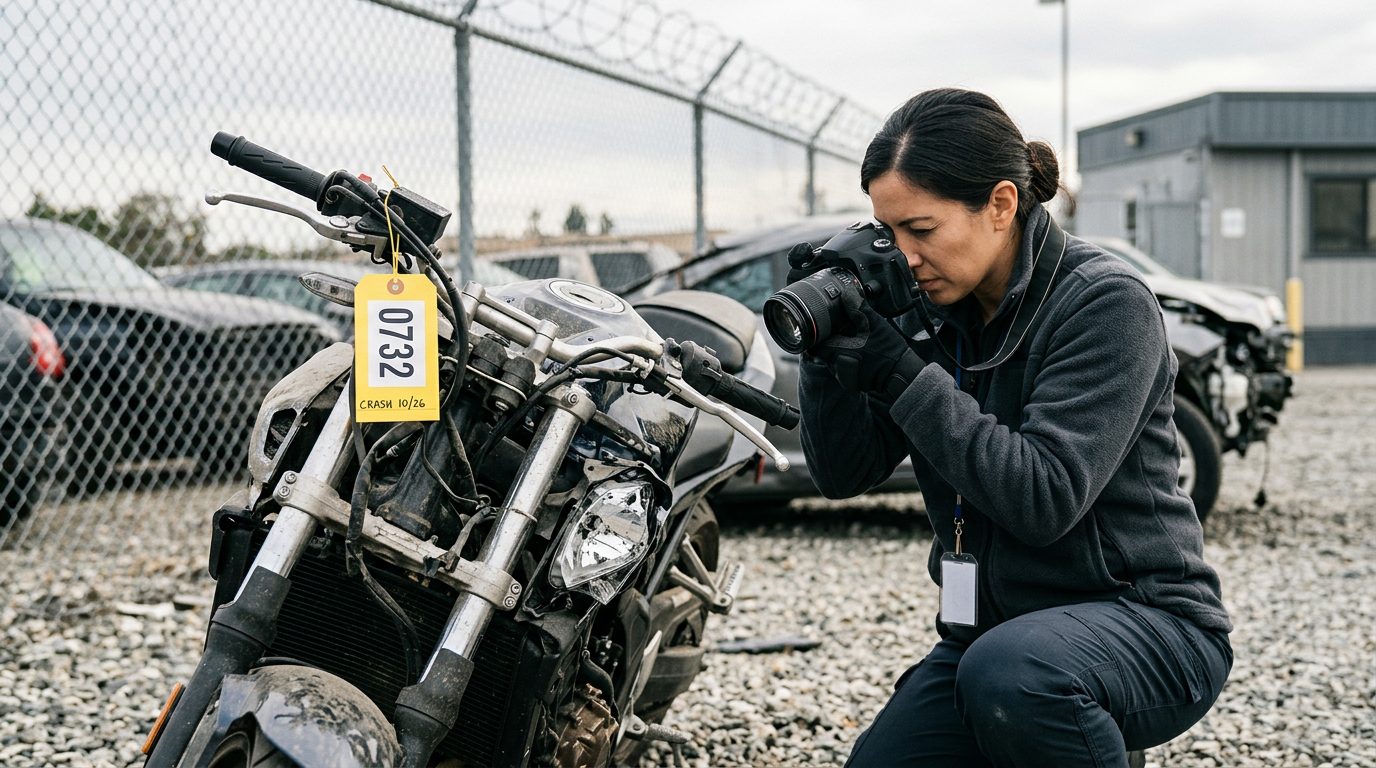
Who Pays Your Medical Bills After a Motorcycle Crash?
Health insurance, Medi-Cal, your own motorcycle policy, and the other driver's insurer can all be part of the picture. Here is how each one may fit into your situation.
By Donald Norman Colvin · Published October 14, 2026
Who Pays Medical Bills After a Motorcycle Crash in California?
The answer to who pays medical bills after motorcycle crash California injuries is usually more than one source. Several sources can pay, often in sequence, and no single source is first in every case. The main ones are your own motorcycle policy, your health coverage, uninsured or underinsured motorist coverage, and the at-fault driver’s liability insurance.
Under Civ. Code § 1714, a person can be responsible for injuries caused by a lack of ordinary care. If another driver caused your crash, that driver may owe you damages, including medical costs. Liability insurance is often how those costs get paid.
Don’t assume one policy will cover everything. Which coverage applies depends on the policy terms, who was at fault, and the facts of the crash. Each source has its own rules, and the order can change as the facts come out. Start a file on day one, even if the injuries seem minor. Keep every bill, letter, and insurance statement. Those papers show what was billed, what was paid, and by whom.
If you're handling your loved one's bills and insurance calls right now, we'd be glad to talk through their coverage in a free, confidential initial consultation. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Your Own Motorcycle Policy: Medical Payments Coverage
Your own motorcycle policy may include medical payments coverage, often called MedPay. MedPay is part of your own policy and is meant to pay medical costs from a crash. Liability coverage works differently. It pays other people when you cause them harm.
MedPay is an optional add-on on many motorcycle policies. If your policy doesn’t include it, you may still have other sources, so keep looking at the rest of this list.
The phrase “full coverage” is informal. It does not promise that medical bills are covered. Your declarations page, which lists your coverages and limits, and any endorsements control what your policy provides. Read them line by line.
Report the crash to your own insurer promptly. Policies usually set notice requirements, and late reporting can create problems. Check your policy’s claim section for the timing rules, and write down the date you called.
Health Insurance, Medi-Cal, and Medicare After a Motorcycle Crash
Health insurance, public programs, and Medicare can all pay for accident-related care, and each follows its own rules. Start by finding out which of these covers you, then tell each one about the crash.
Whether Medi-Cal pays for an accident claim depends on the program’s rules and your eligibility. This page can’t answer that for your situation. Ask the program directly how it handles accident claims, and get the answer in writing.
Tell your providers and health plan about the accident. Accurate coding helps the claim get submitted correctly. Ask each payer whether it expects repayment from a settlement before any money changes hands.
Uninsured and Underinsured Motorist Coverage When the Other Driver Can’t Pay
Uninsured motorist (UM) and underinsured motorist (UIM) coverage are parts of your own policy that may help when the at-fault driver has no insurance or too little of it. UM applies when the other driver has no insurance. UIM applies when the other driver’s limits are too low for your losses.
These coverages matter in a few common situations. The at-fault driver may carry no insurance, carry a policy with limits too low for serious injuries, or leave the scene. Whether your policy includes UM or UIM, and whether it applies to your riding, depends on the policy language. Check your declarations page.
UM and UIM claims usually run through your own insurer. They can have separate notice rules and claim steps. Read that part of the policy before you file. If you’re unsure whether these coverages apply, ask your insurer in writing what it has on file for you. Don’t sign any insurer’s documents until you understand what they say.
The At-Fault Driver’s Liability Insurance and What It Can Pay
When another driver caused the crash, that driver’s liability insurance may pay your losses, up to the policy limits. California law lets an injured person recover money for detriment caused by another’s unlawful act or omission (Civ. Code § 3281). Detriment means loss or harm suffered in person or property (Civ. Code § 3282).
Losses fall into two groups. Economic damages are objectively verifiable money losses, such as medical expenses and lost earnings. Non-economic damages are subjective losses, such as pain, suffering, and emotional distress (Civ. Code § 1431.2).
For example, a rider found 30% at fault could still recover 70% of damages.
The value of any claim depends on your injuries, medical records, evidence of fault, and insurance limits. No general page can say what a particular case is worth. One limit to know: in a motor vehicle case, Civ. Code § 3333.4 bars non-economic losses for a person who was operating a vehicle in violation of Vehicle Code § 23152 or 23153 and was convicted of that offense, subject to the statute’s exceptions. A separate page on how claims are valued explains more.
Hospital Liens, Provider Billing, and Medical Records
Providers may bill you while a claim is still open. Some care is paid only after a claim settles. A PMC article on medical liens explains that treatment may be given right away, with payment deferred until the claim is settled or resolved. That’s why lien questions often come up during an open claim.
Ask every provider whether they are billing you directly or waiting on a settlement. Get the answer in writing. Don’t assume a bill has been paid just because you haven’t heard about it.
Keep copies of every bill, explanation of benefits (EOB) statement, and visit summary. An EOB shows what an insurer paid and what it says you may still owe. Keep a simple log of appointments, too.
Consistent treatment matters. Treatment gaps and mismatched records give insurers room to argue the crash didn’t cause your injuries. Follow the treatment plan your doctor gives you, and tell each provider about every symptom.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
What to Say (and Avoid) With Insurance Adjusters, and Your Next Step
Be careful with what you say to an insurance adjuster, and don’t sign anything you don’t understand. Early calls can shape how a claim is read later.
Avoid guessing about fault. Say what you remember, and say you’re still gathering facts. Don’t minimize your injuries because you feel okay today. Be cautious about recorded statements and early medical release forms. A release of claims can close off future recovery, so read it closely before you sign.
You don’t have to accept a first offer. Take time to understand the numbers and what each payment covers.
If you’re reading this for an injured rider you care about, you may be handling bills, calls, and paperwork all at once. That’s a hard, time-sensitive place to be. You don’t have to sort out the coverage alone. Colvin Accident Lawyers offers a free, confidential initial consultation with no obligation to continue. Contact the firm to talk through the bills and coverage in your situation.
Frequently Asked Questions
Does Medi-Cal cover auto accidents?
It depends on the program’s rules and your eligibility. Ask the program directly how it handles accident claims.
Does full coverage motorcycle insurance cover medical bills?
Not always. Your declarations page and endorsements show what your policy covers.
Who pays medical bills after motorcycle crash California first?
No single source is first in every case. Your own policy, health coverage, UM/UIM, and the at-fault driver’s insurance can each play a role.
Donald Norman Colvin, Colvin Accident Lawyers, Bakersfield, California — responsible for this site.
Common Sources of Medical Bill Coverage
Your motorcycle policy
Review your declarations page and endorsements to see whether your policy includes medical payments or other injury-related coverage.
Your health insurance
Your health plan may cover treatment while a claim is pending, subject to its own terms, networks, and reimbursement rules.
Medi-Cal or other public programs
Eligibility and how accident claims are handled depend on the program's rules. Ask the program directly how it treats auto and motorcycle accident claims.
The other driver's insurance
When another driver may be involved, that insurer handles the claim against its policyholder and may request medical records and other documents.
How Colvin Accident Lawyers Can Help
Free first consultation
Your initial consultation is free, confidential, and comes with no obligation to continue.
Review of your coverage
We can look at your motorcycle policy, health plan, and medical bills to help you understand which sources may apply to your crash.
Focused on accident victims
We represent injured riders, passengers, and families in motorcycle accident cases, and we fight for fair compensation for the losses you have suffered.
Based in Bakersfield
We serve riders across Kern County and nearby communities, including Fresno, Visalia, Lancaster, Palmdale, Delano, and Tehachapi.
Don't Assume Your Bills Are Covered
Coverage depends on your policy terms, the program or plan involved, and the facts of your crash. Before you sign any insurance form, release, or settlement document, ask for an explanation of what it covers.